Financing
Paying for a home you haven't built yet.
Building is financed a little differently from buying. Here is how it works, in plain language, before you talk to a lender.
The short version
Buying pays the seller. Building pays the work.
When you buy an existing house, you get a mortgage and the seller is paid at closing. One transaction, and you own a house that already stands.
When you build, there is no house yet. So the money is released in stages as the work is finished and inspected. That kind of loan is called a construction loan, and you usually pay interest only on the money that has actually been drawn, not on the whole amount from day one.
Many lenders offer a single-close loan, sometimes called construction-to-permanent, that begins as a construction loan and turns into a regular mortgage when the house is done. You go through underwriting and closing once instead of twice.
How a construction loan pays out
Money follows the work.
Your lender releases funds in draws as each stage is completed and inspected. Nobody hands over a lump sum at the start.
-
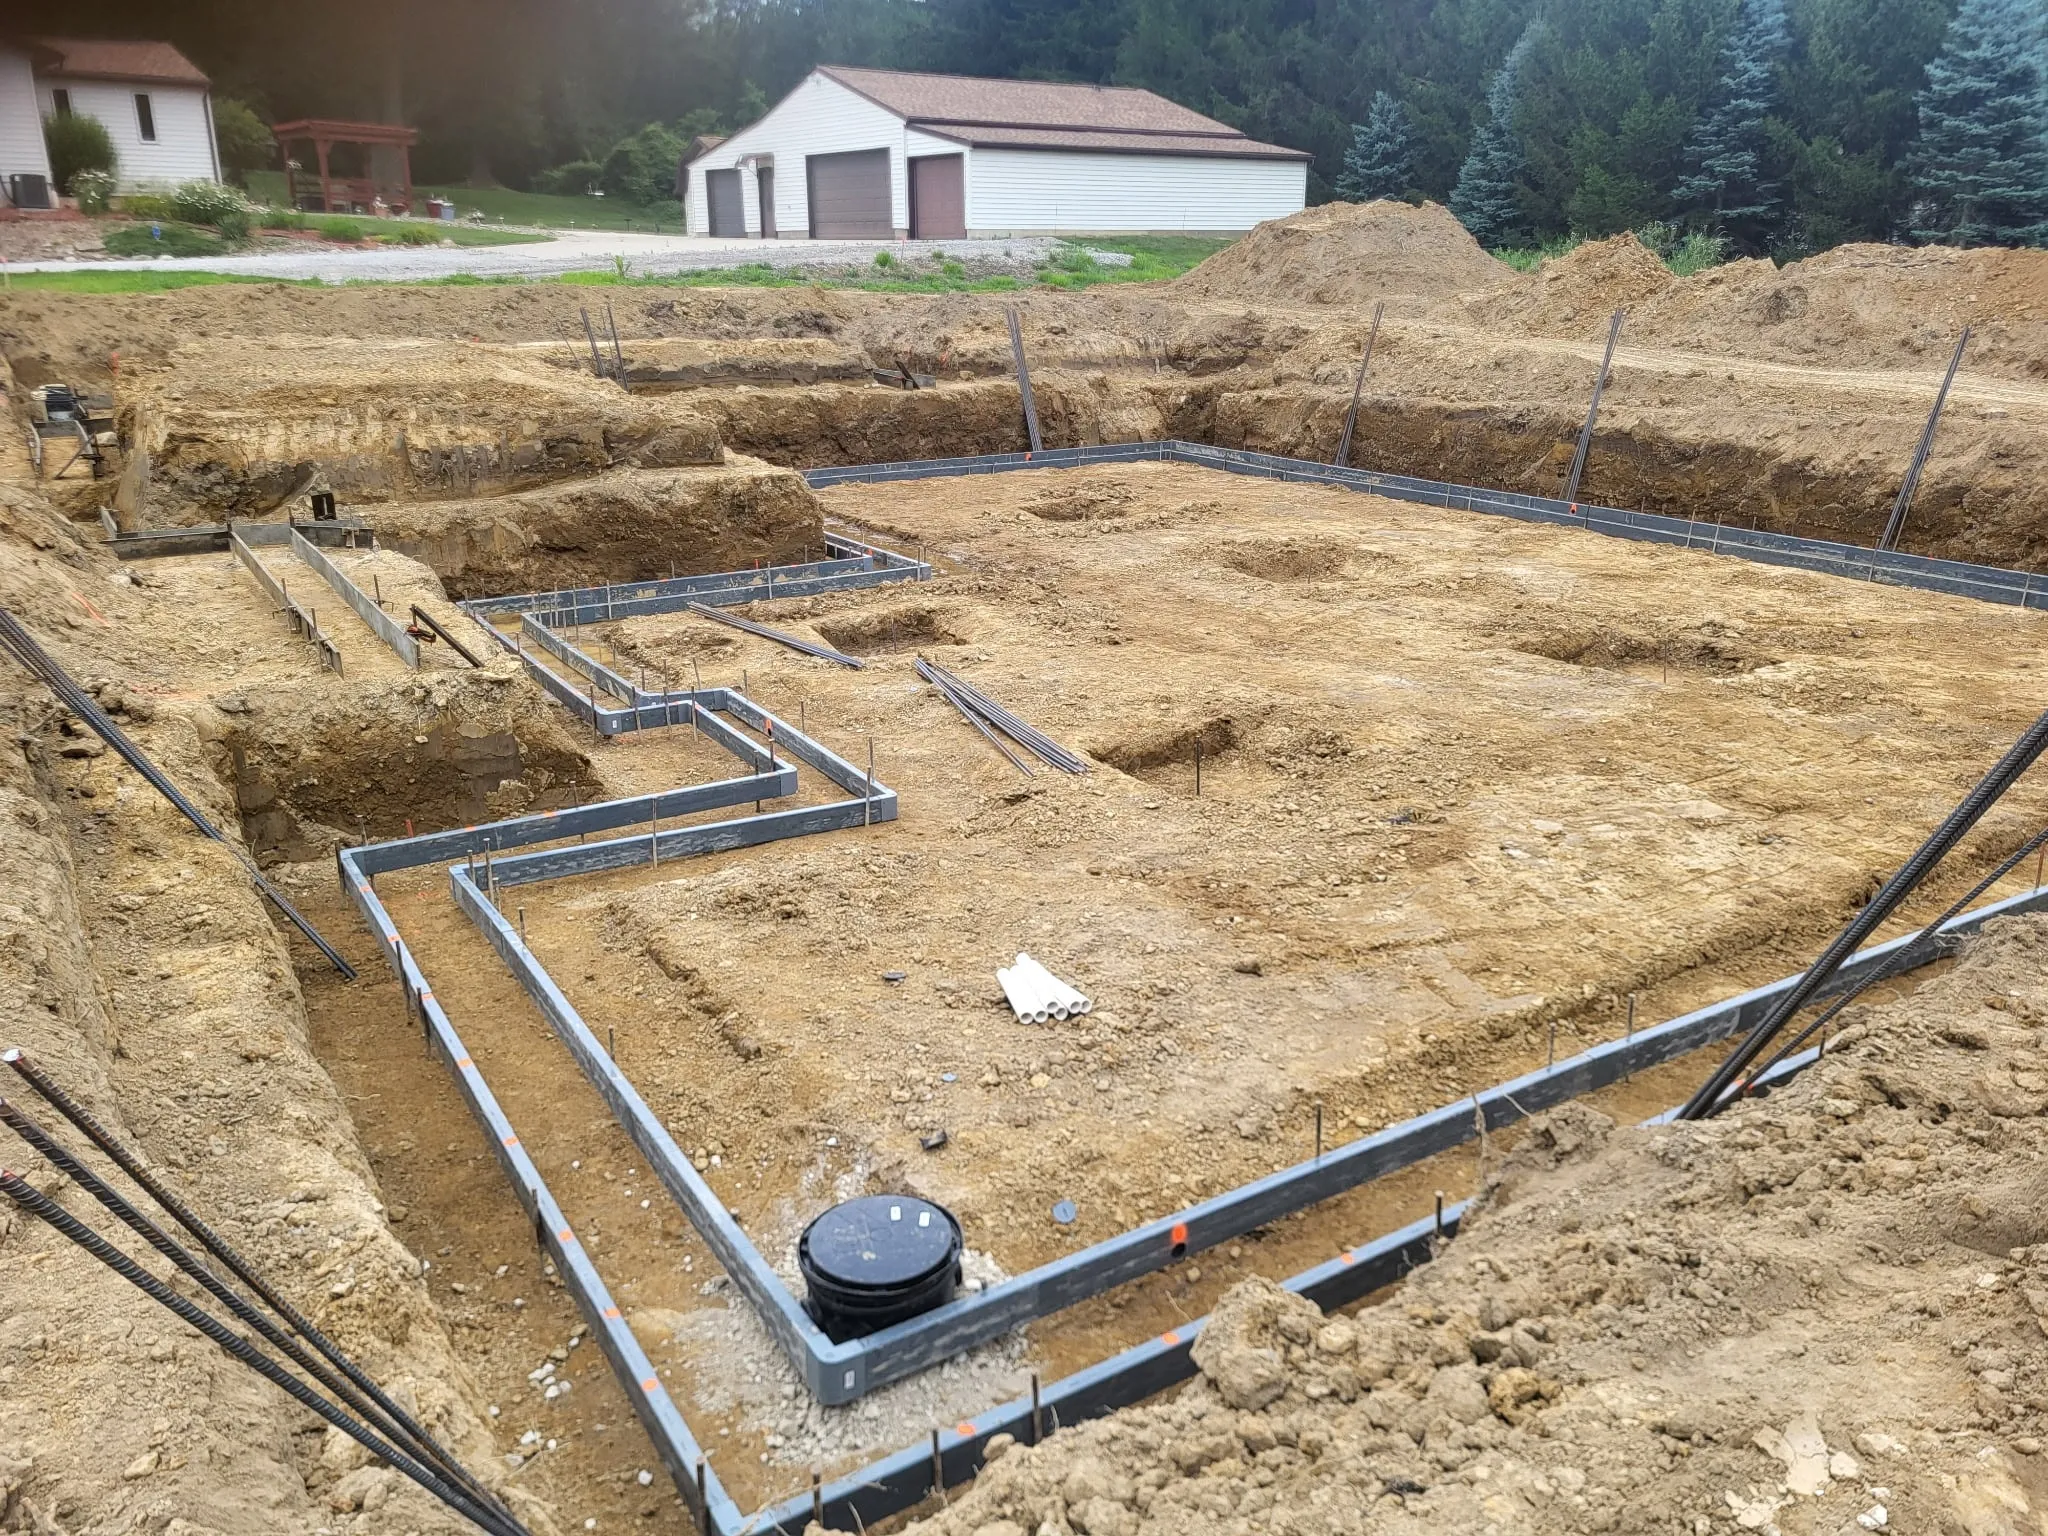
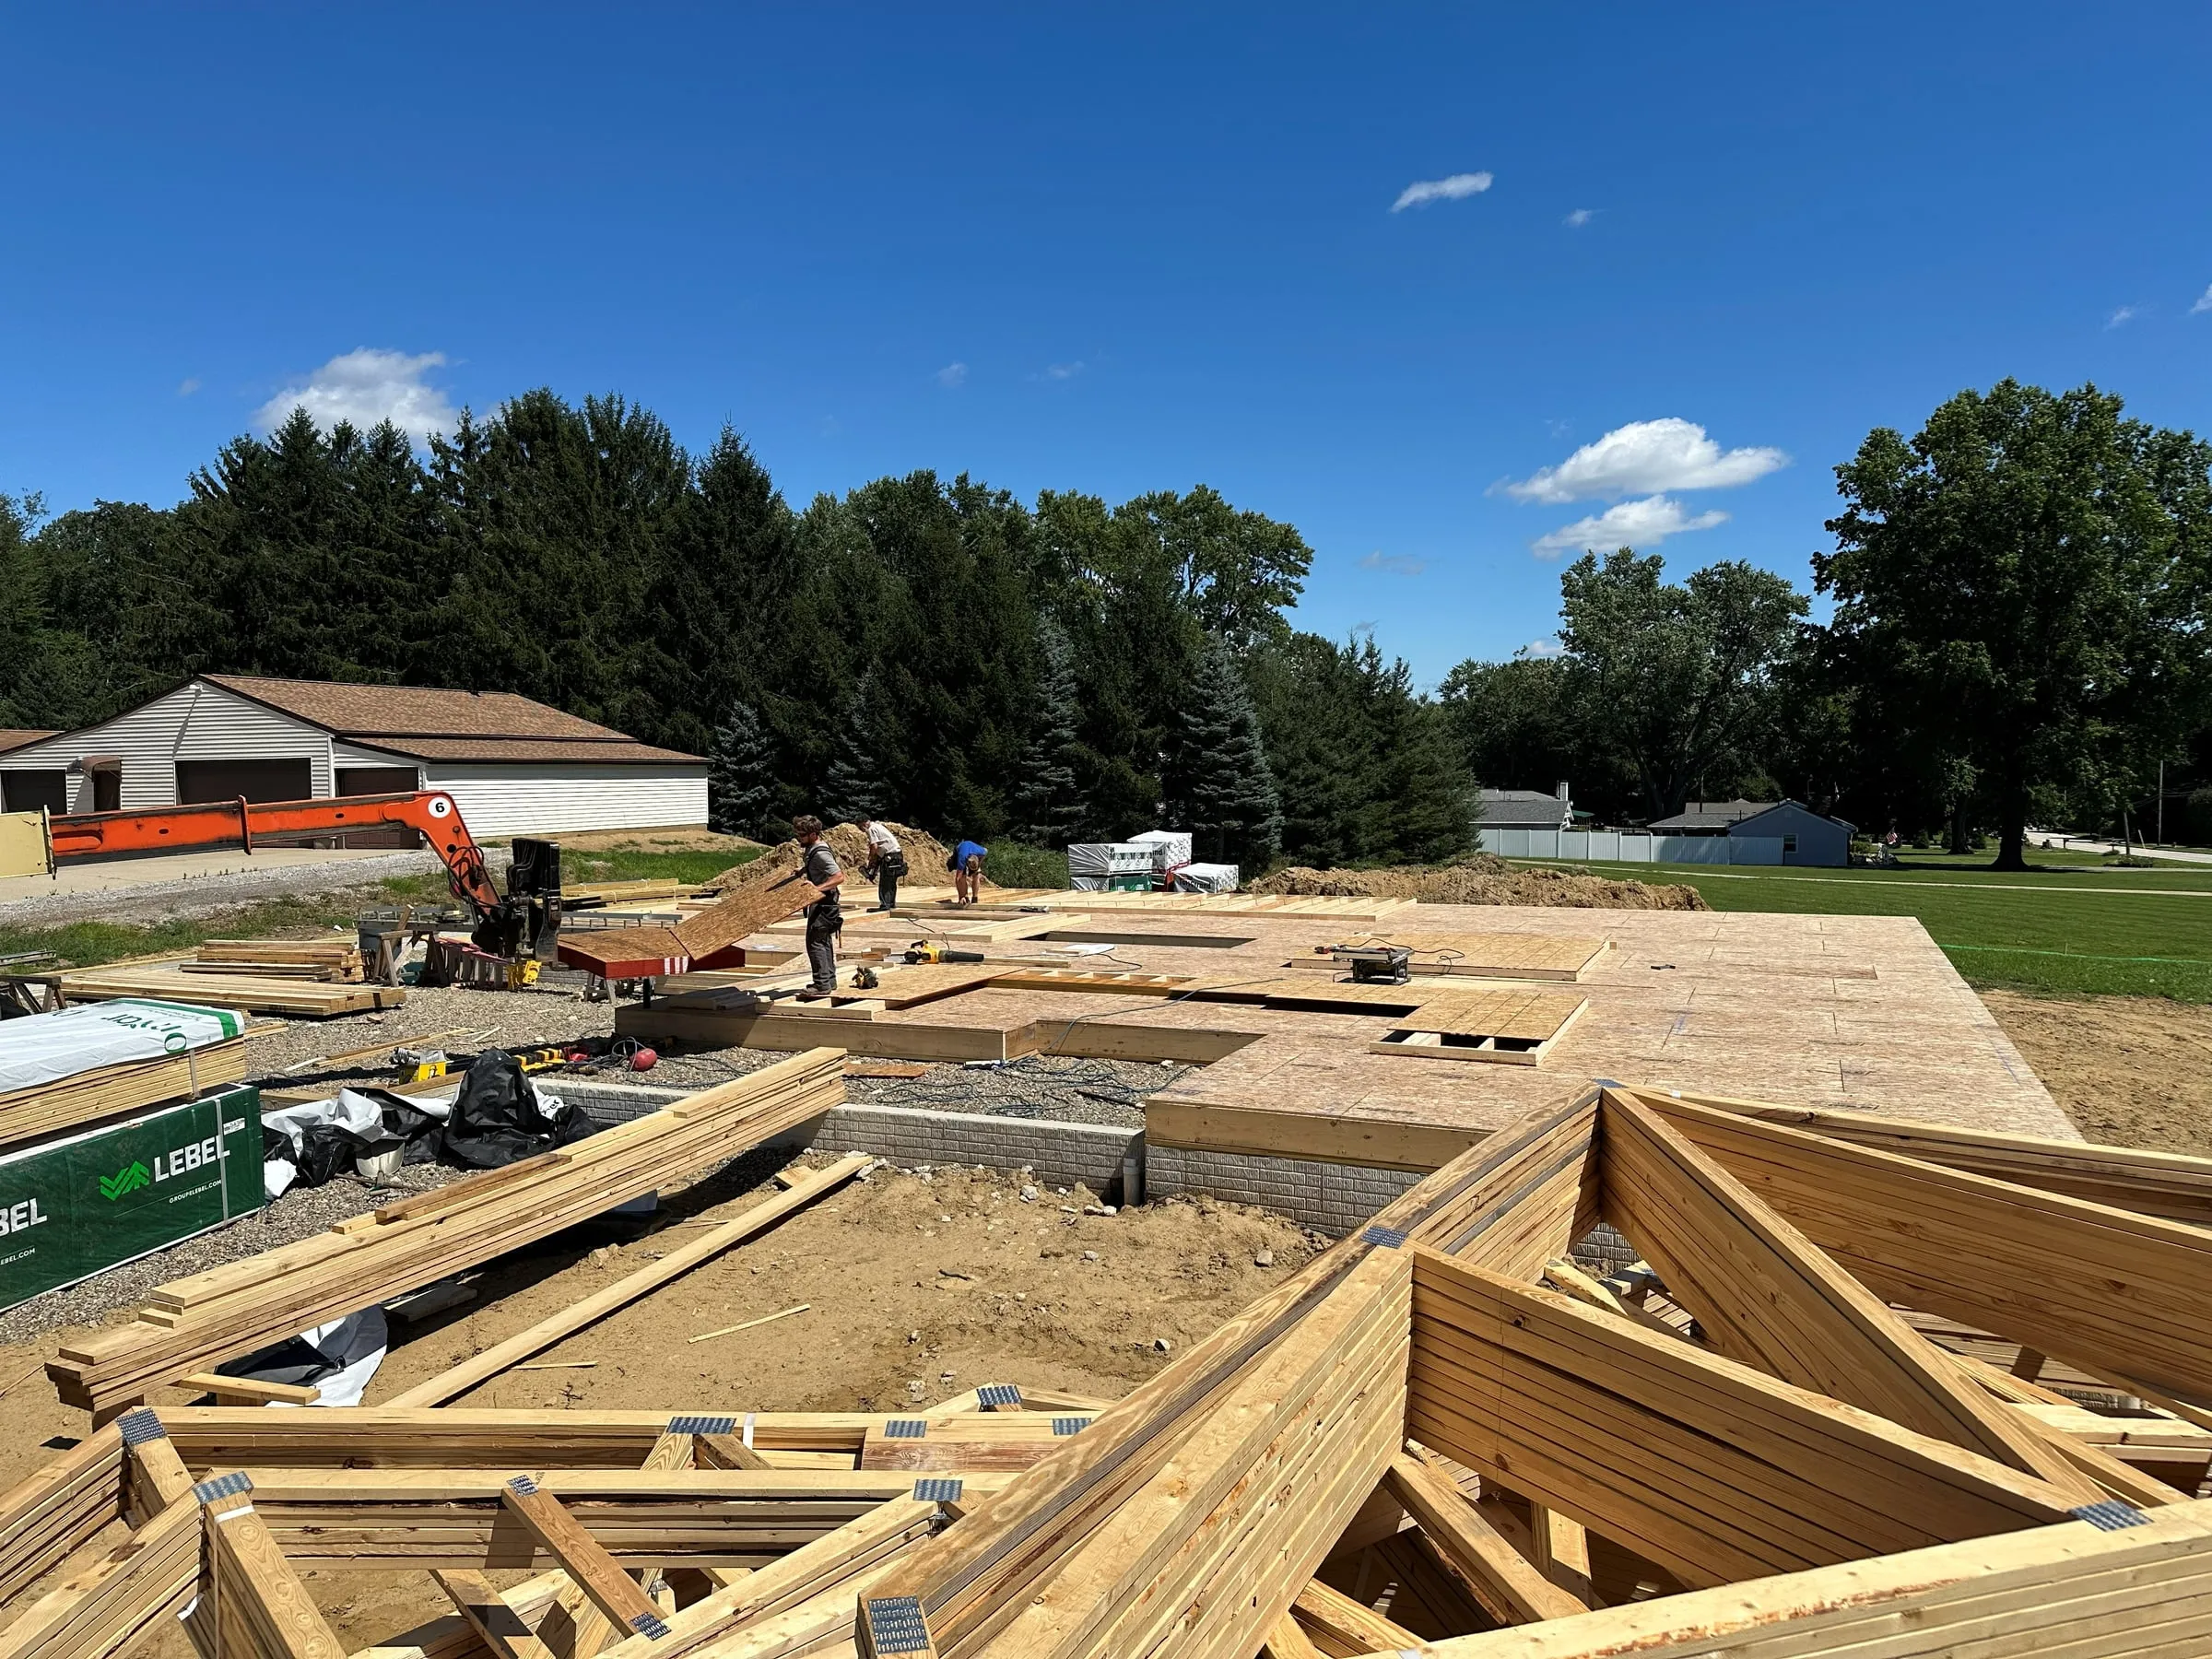
Stage 1
Foundation
The first draws cover site work and the foundation.
-
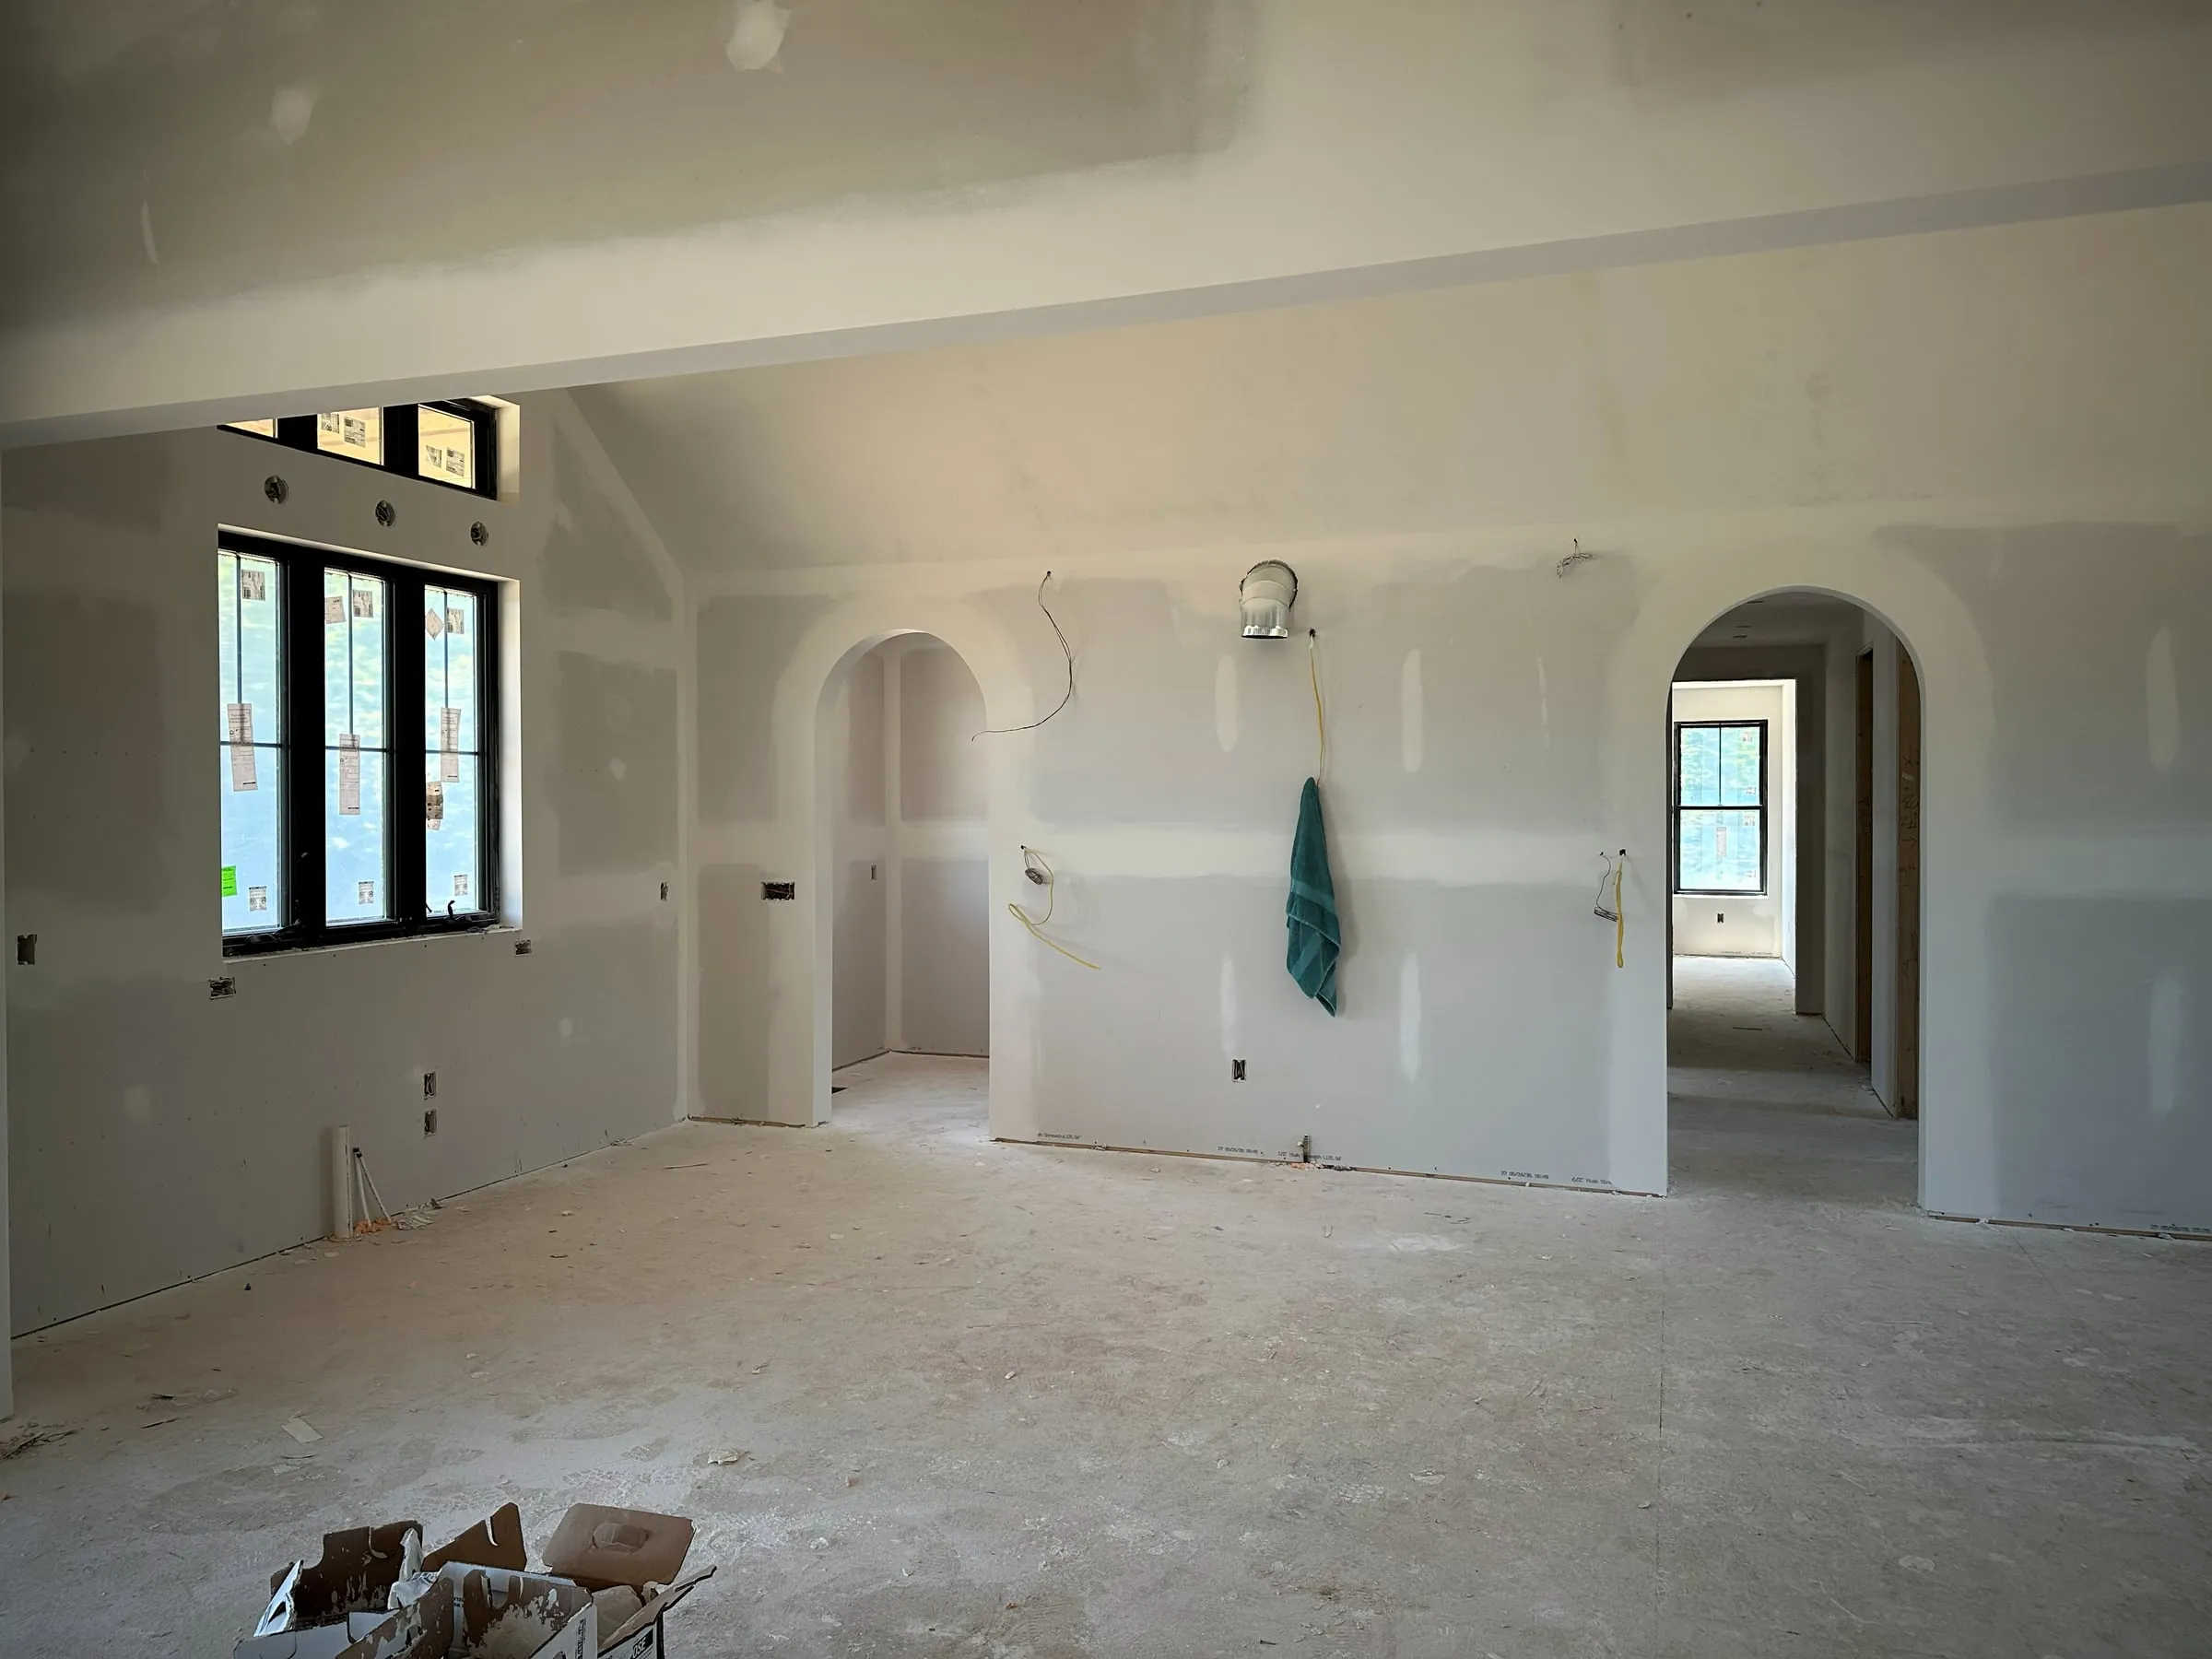
Stage 2
Framing
The house takes shape and the next draw follows.
-
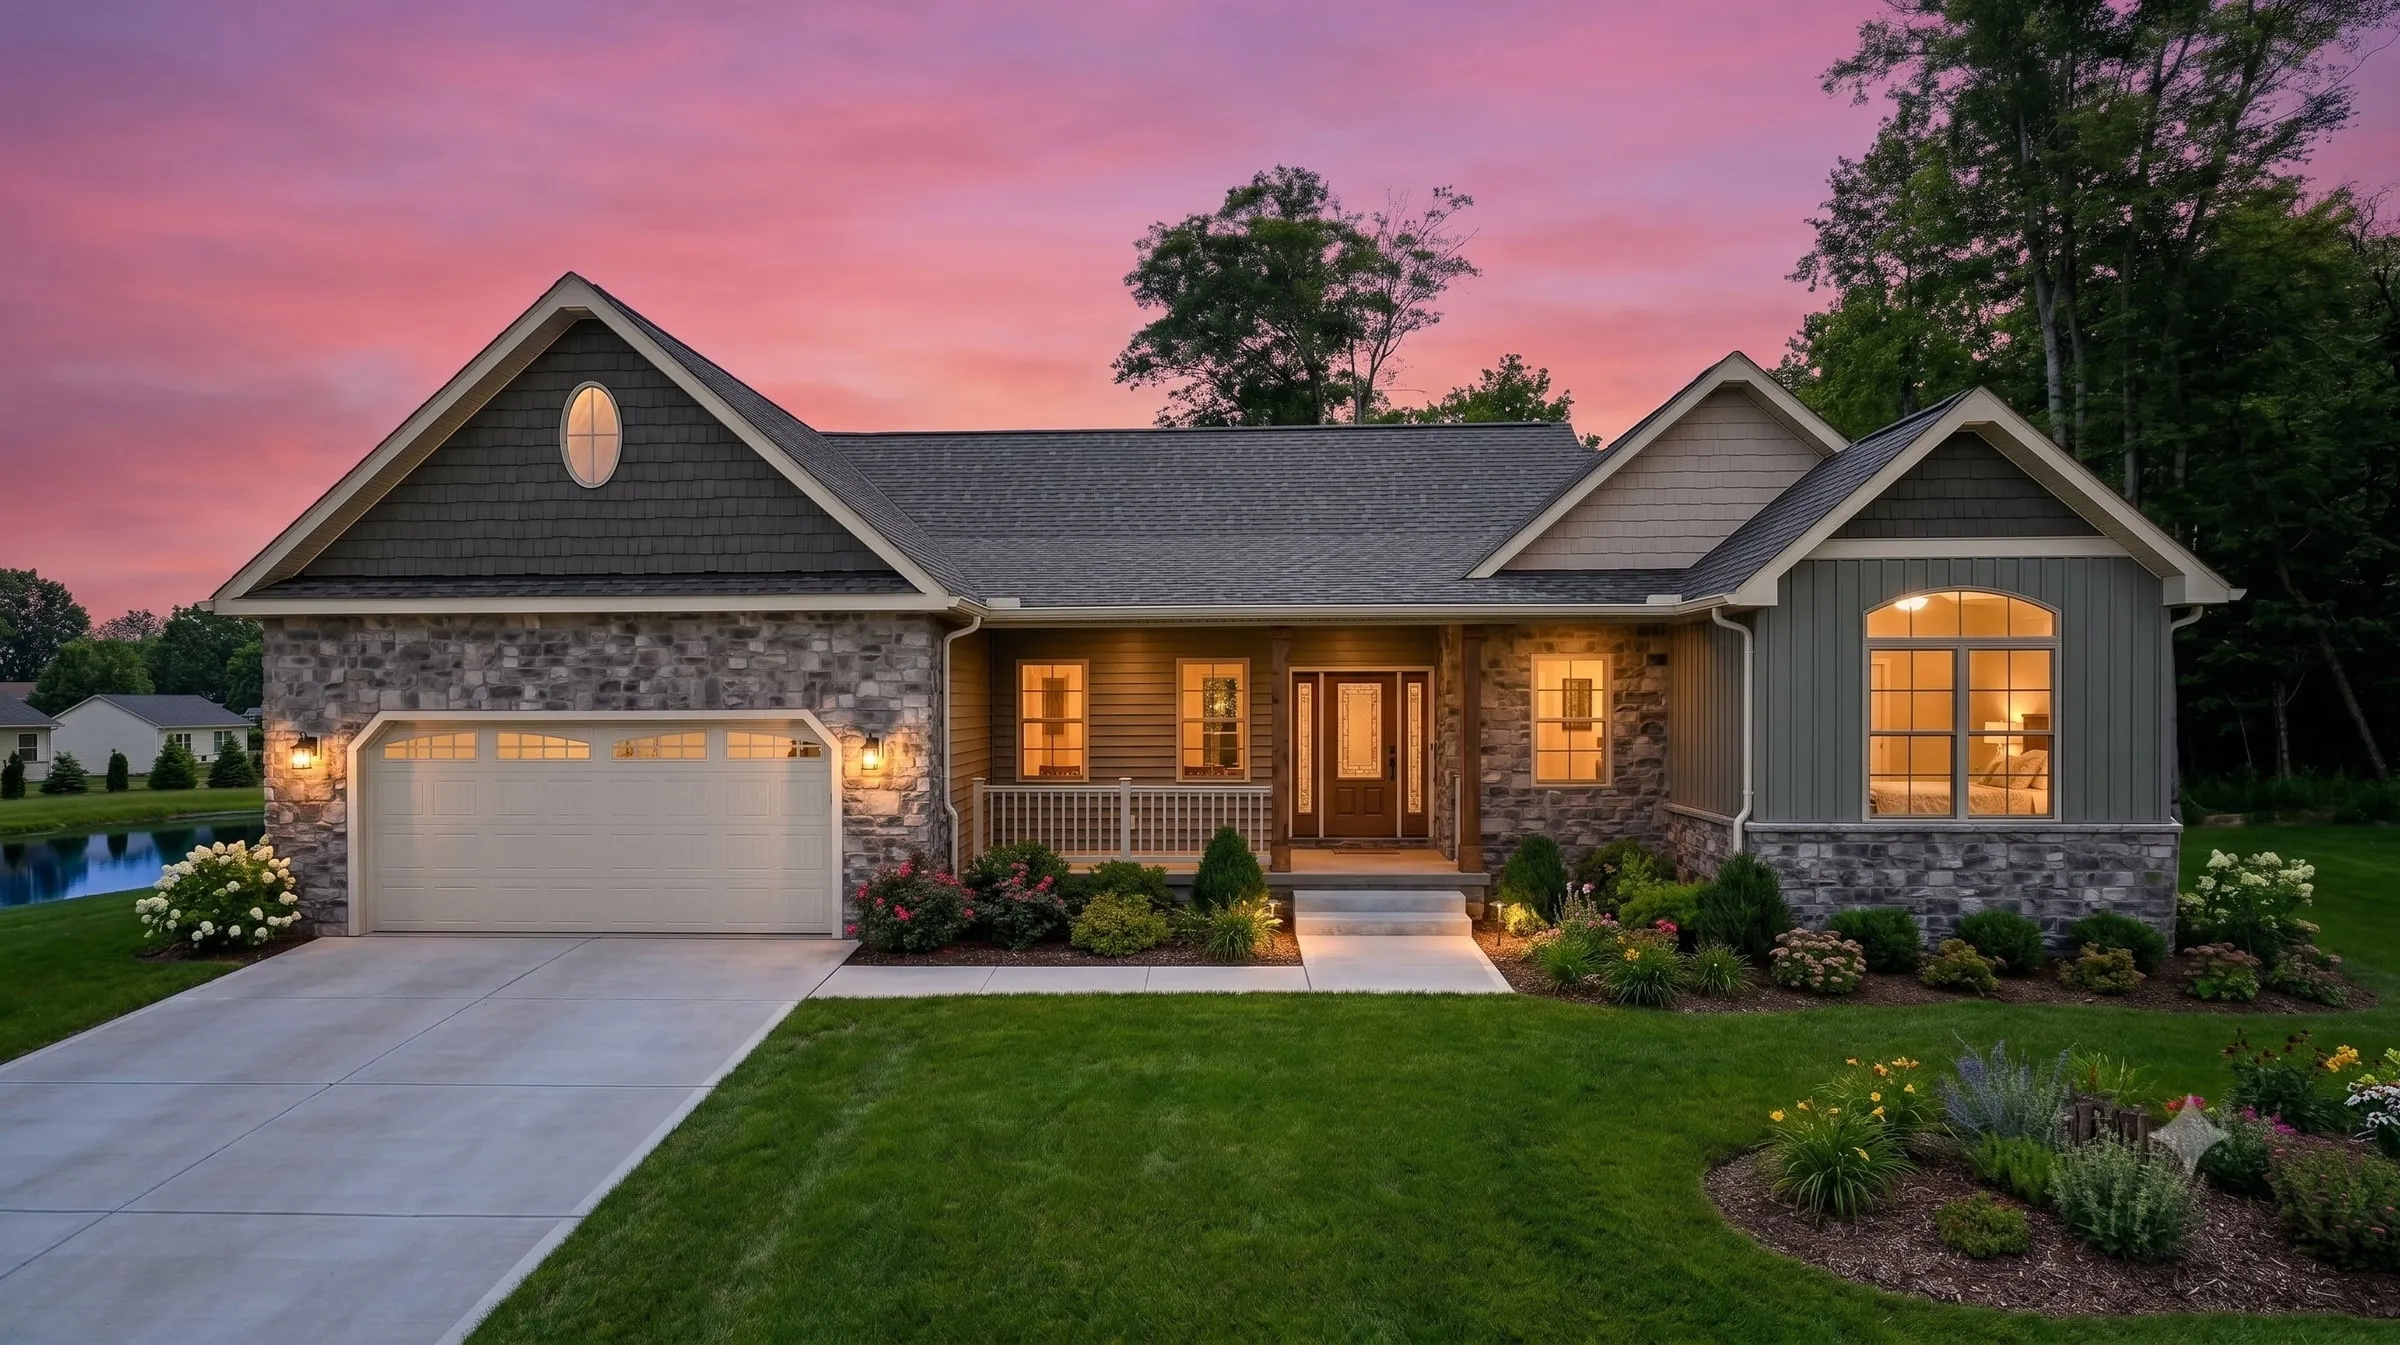
Stage 3
Finishes
Mechanicals, drywall, and interior work.
-
Stage 4
Completion
Final draw, final inspection, and you move in.
Through it all you can follow progress in our online client portal, so you can see what you are paying for.
If you already own land
Your lot may count toward your down payment.
This is the part that surprises people, usually in a good way.
If you own your land outright, lenders will often count its value as equity in the project. That can reduce the cash you need to bring to closing, sometimes substantially.
If you are still paying on the land, the balance usually gets folded into the construction loan. Ask your lender how they handle it, because the answer varies.
Choosing a lender
Ask for one who builds.
Not every lender writes construction loans, and the ones who do it often are far easier to work with. A local lender who knows Northeast Ohio townships and inspectors is worth finding.
A lender to start with
Sharon Bowe, First Federal Lakewood
If you don't have a lender yet, start with Sharon. She is a Mortgage Loan Originator at First Federal Lakewood, an Ohio bank, and she writes construction loans regularly, so you will not spend the first call explaining what a draw schedule is.
ffl.bank/sbowe · NMLS #728228. First Federal Lakewood is an independent bank and not affiliated with Hahn Homes. We are a builder, not a lender, and you are free to finance your home with whoever you choose.
Already have a lender? Bring them in early and we will work with them directly on draw schedules and inspections.
Don't have one yet? Call or text 330-969-2622 and we will point you toward local lenders who write construction loans regularly.
Building on land you own? Our free guide covers what to budget for beyond the house, and how land you already own can count toward your down payment.
What to have ready
Before your first call.
- Recent pay stubs, W-2s, and tax returns
- Bank and investment statements
- The deed or purchase agreement for your land, if you have one
- A rough idea of the plan and square footage you want
- An estimate of what you'd like your monthly payment to be
You do not need every one of these to start a conversation. Bring what you have.
Financing questions
What people ask us.
What is a construction loan?
A loan that funds a home while it is being built. Instead of paying out all at once, the lender releases money in draws as each stage is completed and inspected, and you typically pay interest only on what has been drawn so far.
Do I need two loans to build a house?
Not usually. Many lenders offer a single-close or construction-to-permanent loan that starts as a construction loan and converts to a regular mortgage when the home is finished, so you go through underwriting and closing costs once.
Can the land I already own count toward my down payment?
Often, yes. If you own your lot outright, lenders will frequently count its value as equity in the project, which can reduce the cash you need at closing. If you are still paying on the land, the balance is usually rolled into the construction loan.
When do I start making payments?
On most construction loans you pay interest on the funds that have been drawn while the house is being built, then begin regular mortgage payments once it converts. Ask your lender to walk you through their specific schedule.
Does Hahn Homes provide financing?
No. We are a builder, not a lender. We work alongside whichever lender you choose, handling draw inspections and paperwork on the construction side. If you do not have a lender yet, call or text 330-969-2622 and we will point you toward local ones who write construction loans regularly.
What does the home cost before financing?
At Willow Run at Norton, home prices for our signature plans start at $372,990, with homesites priced separately from $64,900. Fully custom homes on your own land are priced by design. Permits and tap-in fees are included up to $5,000.
Next step
Let's talk numbers.
Tell us what you are thinking about and we will help you figure out what it costs to build it. Or call or text 330-969-2622.
This page is general information about how construction lending usually works, not financial advice. Loan programs, rates, terms, and requirements vary by lender and by your circumstances. Hahn Homes is not a lender and does not arrange financing. Talk to a licensed lender about your situation.